✧ Key Takeaways
- PPF insurance coverage depends on the actual policy, any accessory declaration and the insurer’s acceptance.
- Retain the invoice, product details and dated photos; confirm the insurer’s required documents.
- A manufacturer warranty and accident insurance cover different things.
- There is no universal accessory premium or claim-value threshold established by the 3M product information.
- Compare the expected payout, excess and actual renewal/NCD consequences with the insurer before deciding to claim.
A PPF insurance claim in Malaysia is possible under a comprehensive motor policy, but only if your paint protection film is properly documented and your insurer accepts it as a declared accessory. Most owners only find out the rules after an accident, when it is already too late to fix the paperwork. This guide is the version we wish every Malaysian driver could read on the day they install PPF, not the day they crash.
This guide covers documentation, claim routes and the cost questions to ask your insurer. The 3M product information establishes product specifications and warranty terms, not an entitlement to an insurance payout or a universal NCD outcome.
What a PPF Insurance Claim in Malaysia Actually Covers
For damage to your own PPF, ask whether your policy covers the film and whether an accessory declaration or extension is required. Third-party liability cover is not the same as cover for damage to your own car. A third-party recovery is a separate route. Do not treat a general claims-settlement principle as automatic approval to reapply PPF.
Check your policy schedule and wording for own-damage cover and any extension or accessory declaration required for PPF. Film named on a schedule may still be subject to limits, exclusions, excess and assessment; no document alone guarantees payment.
For a wider primer on what the film does and how long it lasts in local conditions, see our full guide to 3M paint protection film in Malaysia.
Why PPF Insurance Claims Get Rejected in Malaysia
Missing records or a coverage dispute can complicate a claim. Confirm whether PPF is accepted on your policy and what evidence is required before an accident, rather than assuming one document guarantees payment.
Owner reports can illustrate documentation problems but do not establish a universal insurer rule. Use your policy wording, schedule and written insurer response to confirm what applies.
The fix is proactive. Treat installation day as the same day you build your insurance file. If a small studio refuses to give itemised paperwork, that is the red flag. It is also a clear reason to use certified 3M Pro Shop installers instead.
How to Document Your PPF on Day 1 of Installation
Keep installation records while the work and coverage are easy to document. Ask your insurer which evidence it accepts, rather than assuming a universal documentation format or a guaranteed claim saving.
Step 1 — Get an Itemised Invoice by Panel
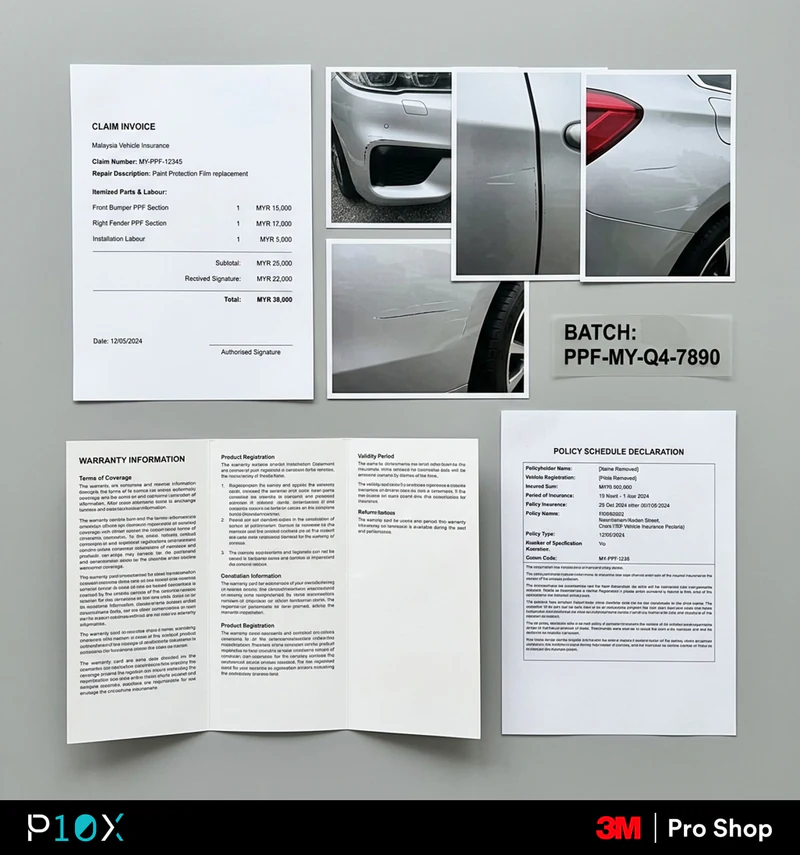
Ask the installer for an invoice that lists each panel separately. Full bonnet, full bumper, fenders, headlamps, side mirrors, door cups, and any other coverage areas should each appear as their own line item with their own RM value. A single line that reads "Full car PPF, RM 19,000" is much harder to claim against than ten lines that add up to RM 19,000, because the adjuster can match each damaged panel to a specific invoice line.
Step 2 — Photograph Every PPF Panel
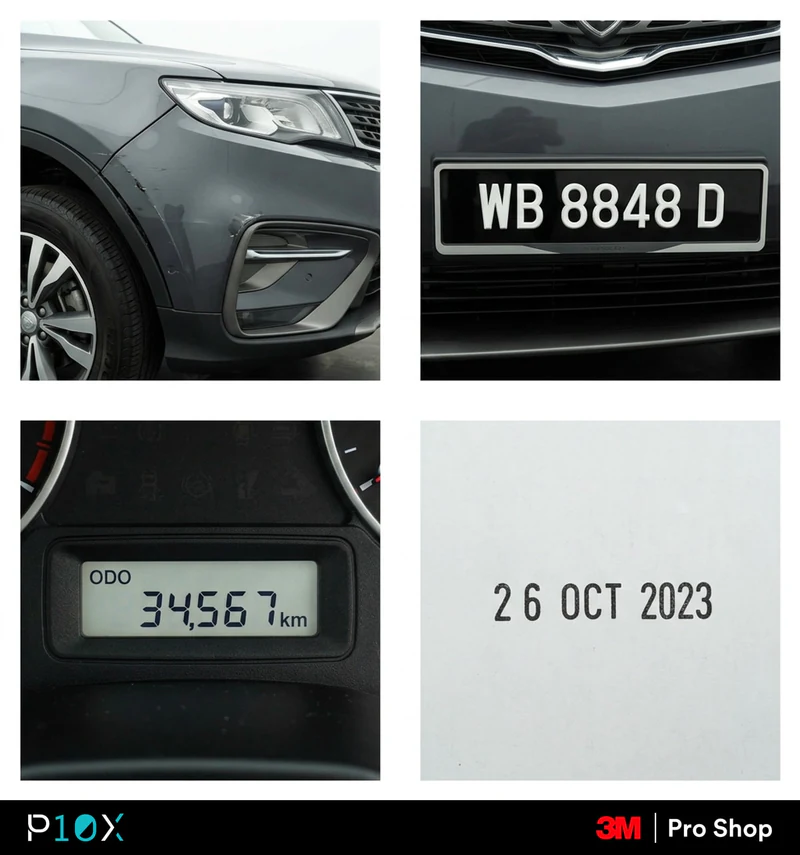
Photograph every panel that received PPF on the day of installation, in daylight, with your number plate visible in at least one wide shot. Capture the panel, the plate, and the odometer where possible, and keep the original timestamps. These photos are your before-state evidence. Save them in a dated cloud folder, not just on your phone.
Step 3 — Save the Batch Number and Warranty Certificate
Ask for the installed series, batch details where available, invoice and written warranty record. Keep them together. A batch number or certificate alone does not authenticate every installed panel; verify uncertain records with the authorised dealer.
Step 4 — Declare PPF Value on Your Policy Schedule
Ask the insurer in writing whether PPF is covered, the endorsement or declaration required, insured value, exclusions, excess, premium and renewal terms. Do not assume a universal 15% loading or one-off payment.
3 PPF Claim Scenarios Every Malaysian Driver Should Know
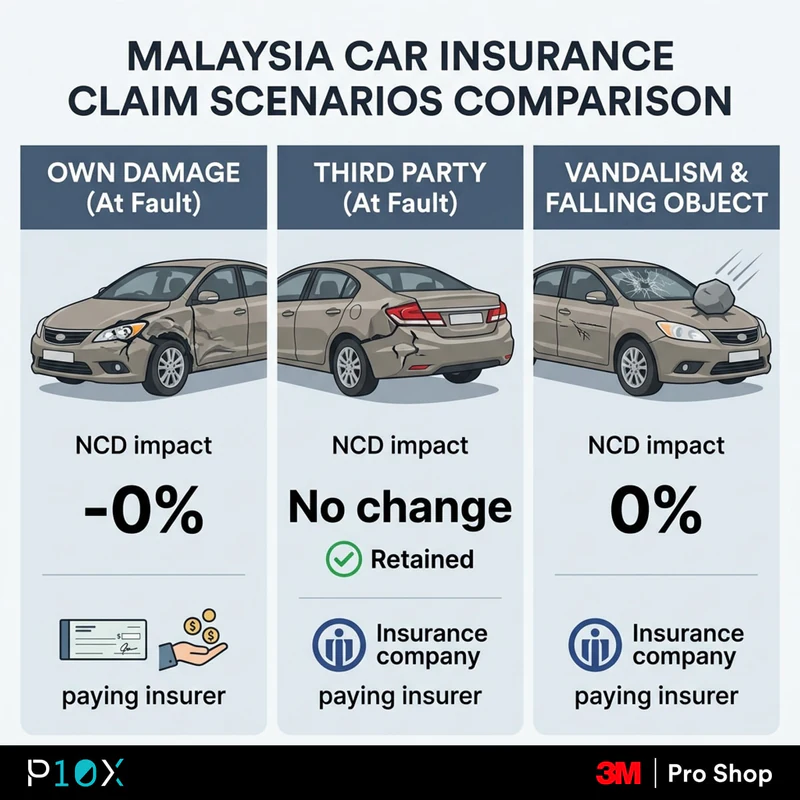
Three claim scenarios cover almost every PPF damage situation on Malaysian roads: you are at fault, the other driver is at fault, or there is no other party involved (vandalism, falling object, special perils). The documentation is similar across all three, but the NCD impact and the paying insurer change. Knowing which scenario applies before you call the insurer protects both your claim and your discount.
Scenario 1 — Own Damage / At-Fault (1st Party Claim)
For an at-fault incident, notify your insurer and ask whether an own-damage claim covers the damaged PPF, what authorisation is needed and how the claim would affect renewal. An invoice and batch record support assessment but do not guarantee reimbursement.
Scenario 2 — Third Party at Fault (Knock-for-Knock)
When another driver may be liable, ask the insurer whether a third-party claim or an eligible own-damage knock-for-knock route applies. An ordinary own-damage claim is not automatically NCD-preserving. Liability, eligibility, documentation and the insurer’s handling must be confirmed.
Scenario 3 — Vandalism, Falling Object, Special Perils
For vandalism, falling objects or weather-related damage, check the exact covered peril and any required extension. These causes do not all share one cover rule or NCD outcome.
PPF Insurance vs PPF Warranty: Don't Confuse These Two
The PPF warranty covers bubbling and cracking: five years for Series 150, three for Series 100 and 50. Accident insurance is separate and depends on policy, event and acceptance.
Ask the authorised dealer to assess suspected bubbling or cracking under the written warranty. Self-healing applies to minor film scratches, not stone-chip damage, deep cuts or missing material. Accident damage may be assessed separately by the insurer.
| Aspect | 3M Manufacturer Warranty | Motor Insurance (Comprehensive) |
| What it covers | Bubbling and cracking under the written terms | Collision damage, vandalism, falling objects, fire, flood (if covered) |
| Who you contact | Your 3M authorised dealer | Your motor insurer or panel workshop |
| Term in Malaysia | Series 150: five years. Series 100 and 50: three years. Confirm the written terms. | For the duration of your policy year, renewable annually |
| Affects NCD? | No | Yes, depending on the scenario |
| Key proof needed | Warranty card, IC, plate number, dealer record | Itemised invoice, panel photos, schedule entry, police report (where required) |
To see the compare 3M PPF Series 150, 100 and 50 breakdown side by side, with warranty terms and pricing, see our dedicated comparison guide. For the routine that keeps both warranty and insurance angles healthy, our PPF aftercare in Malaysia guide walks through the wash and inspection routine in detail.
Common Mistakes That Wreck Your PPF Claim
These are documentation and decision-making checks, not a verified ranking of why Malaysian claims fail. Confirm the insurer’s procedure before authorising repairs or settling liability.
Mistake 1 — Skipping the Itemised Invoice
An itemised invoice can help an assessor link the damaged panels to the installed film and value. A single-line invoice does not by itself establish rejection or a particular depreciation rate; ask what evidence the insurer accepts.
Mistake 2 — Letting NCD Loss Cost More Than the Claim
For a full bumper, the approved medium-vehicle PPF guide is RM2,250 across all three series, not a generic RM600–1,200 full-bumper price. Partial coverage or another vehicle requires a quote. Compare that with the actual excess and NCD consequences.
Mistake 3 — Going to a Non-Panel Workshop First
Contact the insurer promptly and confirm the approved workshop and authorisation process before dismantling or reapplying film. Preserve evidence and follow any emergency safety requirements.
Mistake 4 — Negotiating With the Third Party Directly
Do not sign a private settlement without understanding its effect on your claim rights. Hidden damage and liability can complicate the decision; obtain insurer or qualified advice rather than assuming a cash payment always preserves NCD.
When Filing a PPF Claim Beats the NCD Hit
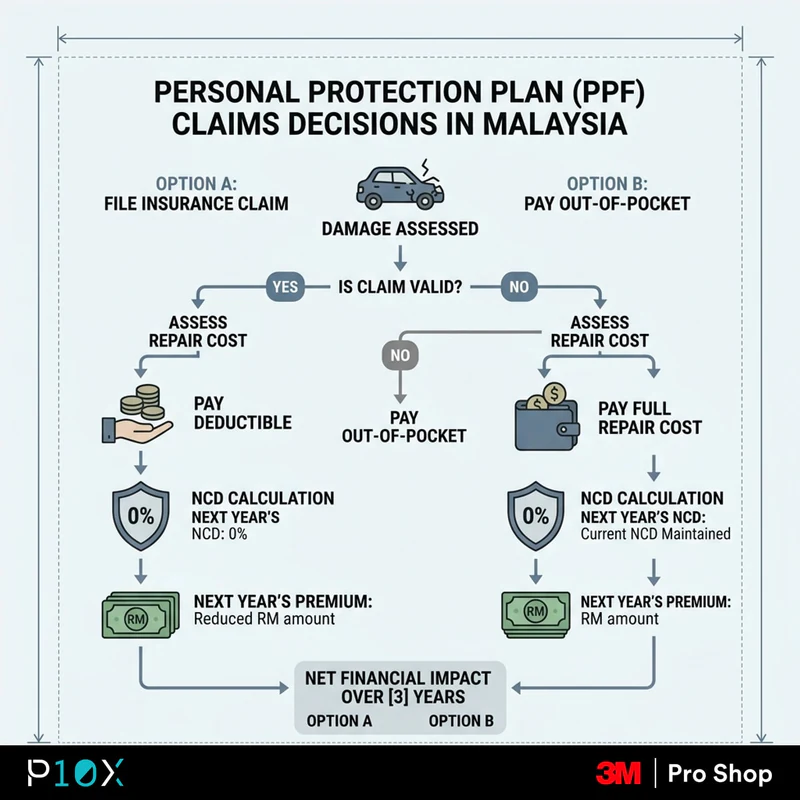
Before filing, ask the insurer how the proposed claim route affects your NCD and premiums over subsequent renewals. No universal reset, recovery timeline or ringgit uplift should be inferred from the 3M product information.
For a medium vehicle, the PPF guide lists a Series 150 full bonnet at RM2,050 and a full bumper at RM2,250. Get the actual repair and reapplication quote, expected insurer payout, excess and renewal impact. Those figures—not an assumed C-Class premium or RM2,500 cutoff—determine the cost comparison.
Windscreen claims may follow a separate policy endorsement. Confirm its coverage and NCD treatment with the insurer rather than assuming it is the only possible NCD-preserving route. Our windscreen NCD guide covers the questions to ask.
| Decision input | What to obtain |
| Repair and PPF cost | Actual itemised quote and damaged-panel scope |
| Coverage | Insurer confirmation that the film and event are covered |
| Net payout | Approved amount after excess and any applicable deductions |
| NCD and renewals | Insurer-specific consequences for the proposed claim route |
| Decision | Compare these actual figures; do not use a universal price cutoff |
For owners weighing whether the original PPF spend was worth it, our PPF investment ROI piece runs the long-term numbers across common Malaysian cars.
Ask Which Claim Documents the Outlet Can Provide
Ask the outlet which documents it can provide. The approved product source does not establish a universal Claim Pack or guarantee every document an adjuster may require.
Request the following where available and check what your insurer requires:
- An itemised invoice with panel-by-panel pricing.
- The 3M PPF batch number and series designation (Series 150, 100, or 50 Gloss).
- Date-stamped panel photos taken in studio lighting.
- A 3M e-warranty card under your name and IC.
- A short declared-accessory letter you can forward to your insurer or agent.
- Panel workshop coordination guidance if a claim ever happens.
Gather original installation records and ask the insurer what further evidence it accepts. Do not assume an outlet can authenticate unknown film or issue an accepted retrospective report.
For an EV or recently launched vehicle, retain the same clear product and installation records. Do not assume an insurer applies stricter PPF scrutiny simply because the car is electric.
How to Set Up Your PPF Claim Before Any Accident
Prepare records when film is fitted: invoice, product and panel details, photos and any required declaration. Before claiming, confirm coverage, authorisation, excess and NCD consequences with the insurer. Documentation helps assessment; it does not guarantee a payout.
Find out the best protection for your car
Visit a 3M Pro Shop and discover the cost-effective 3M Protective Film and Window Tint
FAQ: PPF Insurance Claim Malaysia
Is PPF covered by car insurance in Malaysia?
PPF may be covered if the insurer accepts it under your actual policy and any required declaration or extension. Obtain written confirmation of the cover, limits and exclusions; do not assume all comprehensive policies cover the film.
Will claiming PPF affect my NCD in Malaysia?
It depends on the policy and claim route. Ask the insurer to confirm the NCD and renewal consequences in writing; an ordinary own-damage claim is not automatically equivalent to an eligible knock-for-knock claim.
How do I prove my car had PPF before the accident?
Show the itemised installation invoice, dated panel photos, the 3M batch number, and the e-warranty card under your name. If PPF is also listed on the policy schedule as a declared accessory, that combination is the strongest proof an adjuster can ask for.
Can I claim PPF from the third party's insurer if they are at fault?
A third-party recovery may be available if liability and coverage are established. Ask about the appropriate route and whether an eligible own-damage knock-for-knock arrangement applies. Do not assume the PPF line or NCD outcome is guaranteed.
Does declaring PPF as an accessory increase my premium a lot?
The additional premium and renewal charges depend on the policy. Obtain a written quote rather than applying a generic 15% rate.
How long does a PPF insurance claim take in Malaysia?
Ask the insurer for its current process and expected timetable. Assessment, liability, authorisation and reapplication affect timing; no universal two-to-four-week Merimen timeline is established by the product source.
Can I claim partial PPF (just the damaged panels) or only full re-application?
Ask whether the insurer will authorise reapplication on the damaged panels and how it values that work. An itemised invoice supports assessment but does not guarantee approval of a partial or full replacement.
What is the difference between a PPF warranty claim and a PPF insurance claim?
Warranty concerns covered bubbling and cracking under written terms. Accident insurance depends separately on the policy and event; paperwork does not guarantee payment.